
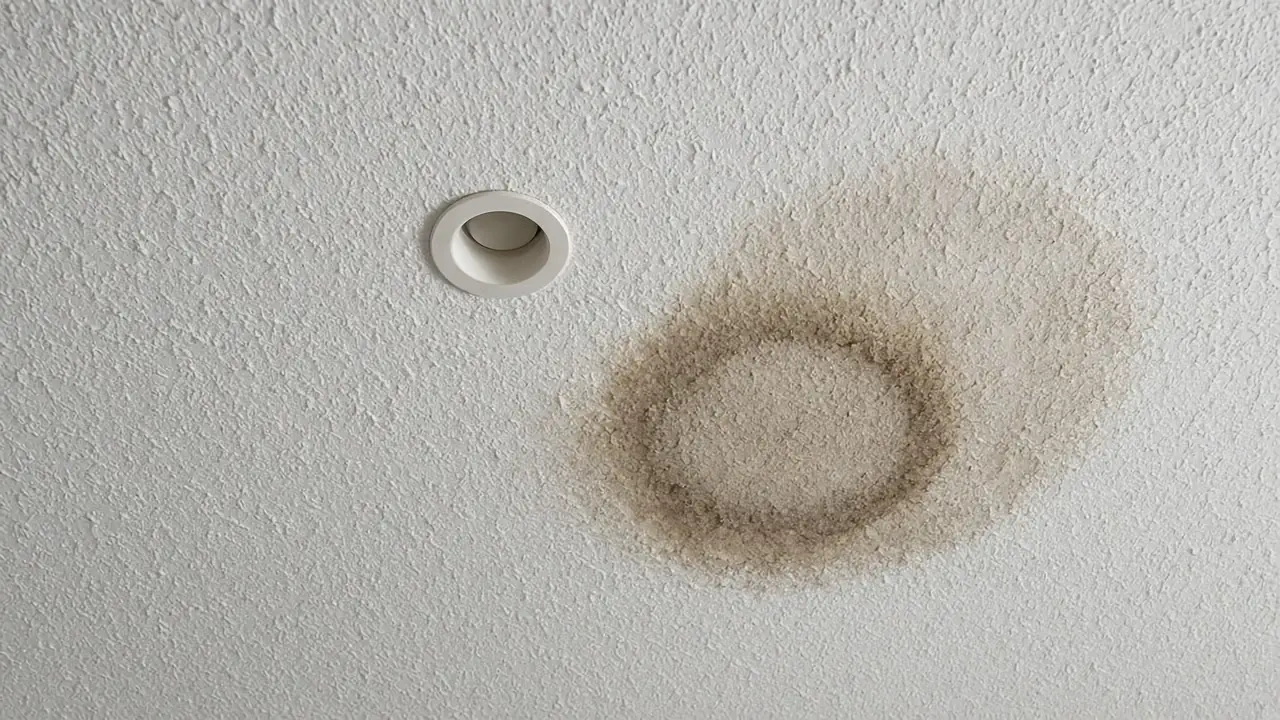
We do not handle claims
This page is general information. We are not an insurer or an adjuster, we do not file claims and we cannot say what your policy will cover. What follows are sourced examples of limits that exist, so you know what to look for in your own papers.
One insurer's mold limit, as an example
Citizens' worksheet for HO-3 homeowners coverage puts a $10,000 cap on fungi, rot and bacteria and says that cap cannot be raised, dropped or changed. (Citizens) The HO-6 worksheet for condo unit owners shows the same $10,000 limit, plus a $2,000 loss assessment limit. (Citizens) Neither one covers sewer or drain backup.
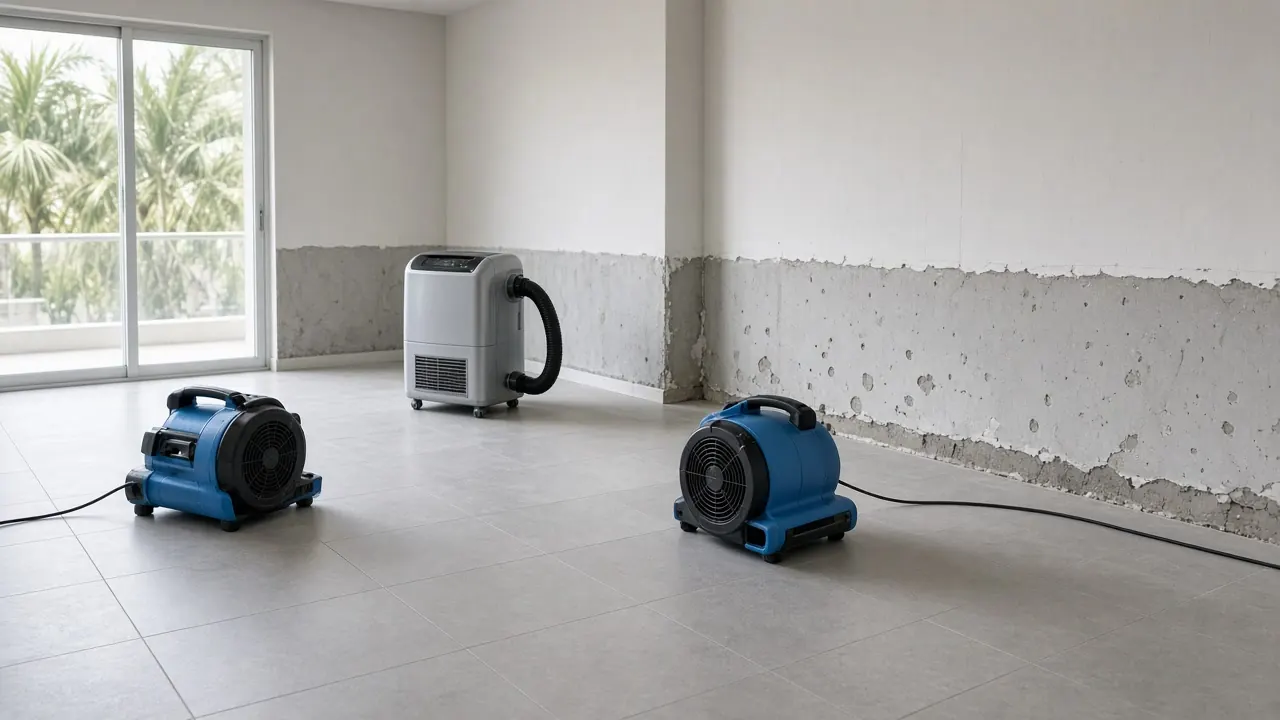
That is one insurer's form. Private insurers write their own, and your own policy governs. Look for words such as fungi, mold, rot and bacteria on the declarations page and in the endorsements list.
Flood is a separate policy
Many Miami-Dade homes sit in FEMA flood zones. In the City of Miami, about 42 percent of mapped buildings are in special flood hazard zones. (Miami-Dade LMS) A standard home policy generally does not behave like a flood policy, so check whether you have a separate flood policy.
The federal flood policy and mold
The federal flood policy has its own mold rule. Damage that comes mainly from a condition the policyholder controls is not covered, and the policy names neglecting to inspect and maintain the property once the water recedes. (44 CFR 61) So after a flood, the clock on drying and checking starts early. EPA's target for drying wet areas is the first one to two days. (EPA)
Power failure after a storm
The same flood policy leaves out losses from an outage unless it flows directly from flood damage to the equipment. (44 CFR 61) A shut-up home in that heat can grow mold even when the storm did no obvious damage. Read what your policy says about that before you assume.
The assignment of benefits ban
For residential property policies written in 2023 or later, Florida does not let a policyholder hand over post-loss benefits. Any attempt is void and unenforceable. (Fla. Stat. 627.7152) There is one carve-out: someone you formally authorize, such as a family member, guardian or management company, may handle the claim for you. (Fla. Stat. 627.7152)
The practical rule: nobody who cleans or dries your home should ask you to sign over your claim. If someone does, stop and ask your insurer.
Record what happened, in order
Whatever your policy says, the best protection is a plain timeline. Note the date you found the water, when it was stopped, who looked at it and when drying began. Keep photographs of damaged materials before anything is thrown away. If a contractor asks you to approve work, ask for the scope and the price in writing first. A dated record is useful to an insurer, an association and a landlord alike.
A short checklist
- Find the fungi or mold limit and the deductible on your declarations page.
- Ask whether water backup and flood are covered, and under which policy.
- Photograph the damage before anything is removed.
- Dry affected areas quickly and keep receipts.
- Do not sign an assignment of benefits.
- Report the loss to the carrier in writing and keep a copy.
Questions for your agent or carrier
- What is the mold or fungi sub-limit, and does it include testing and removal?
- Does a sudden pipe leak change how mold is treated compared with a slow one?
- What do I have to do within a set period after discovering damage?
- Is water that comes in through the slab or a doorway flood, and which policy answers it?
- Do I need your written approval before drying or demolition starts?
Write down the answers and the name of the person who gave them.
Where we fit
We connect you with local companies for assessment, cleanup and drying. The contractor sets its own price. Our $100 credit is separate from insurance and covers a first booking made on this site, after you book and the company quotes the job. Send your address, and we can point you to the right first company.